2026-08-14 · Mike Sullivan
Hail & Storm Damage Roof Repair in Houston: What Insurance Actually Covers
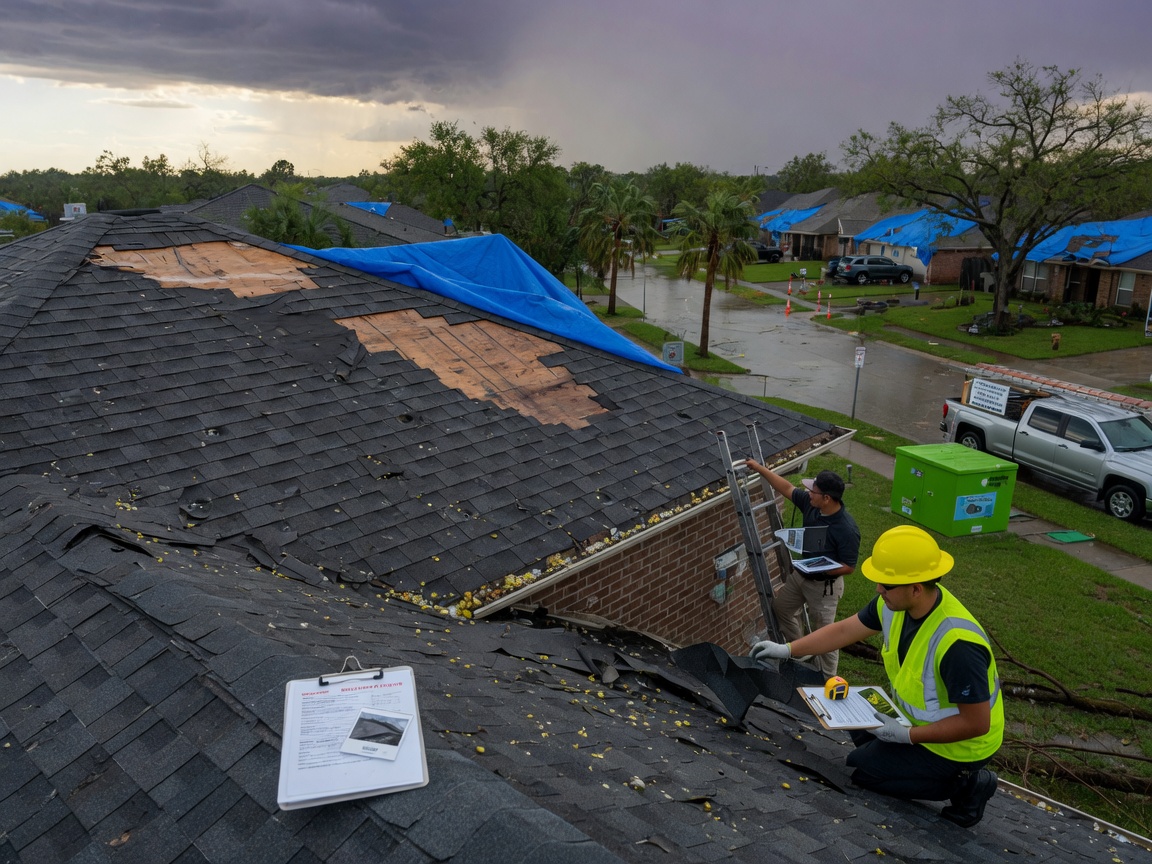
Houston homeowners insurance typically covers hail and storm damage to roofs when it results from a sudden event like a hailstorm, with approved claims often ranging from $4,000 to $12,000 for partial repairs depending on square footage and material. Coverage hinges on proving the damage occurred during the policy period rather than from ongoing deterioration. Policies in Harris County generally exclude cosmetic dents without leaks or damage from lack of maintenance.
How Houston's Climate Creates Hail and Storm Claims
Houston's subtropical climate produces hot humid summers and occasional severe spring storms that drop hailstones large enough to dent asphalt shingles and metal panels. These events often affect neighborhoods such as the Heights and Montrose where older roofs show impact craters visible from ground level. Wind-driven rain during the same storms can force water under flashing around chimneys and vents, leading to interior leaks that require prompt roof repair. Homeowners near landmarks like Minute Maid Park report similar patterns after summer supercells. Insurance adjusters look for fresh granule loss and cracked shingles that align with weather reports rather than uniform aging across the entire surface.
What Standard Policies Cover for Hail and Storm Damage
Most Texas homeowners policies cover replacement cost for hail-damaged sections when the storm is documented by local weather data, including removal of debris and installation of matching materials. This extends to storm damage roof repair that addresses punctures or displaced shingles but stops short of full roof replacement unless more than 50% of the surface is affected. Wind damage that lifts shingles or tears underlayment qualifies when photos show lifted edges and missing fasteners. Claims for leaks following a storm often include drying and minor ceiling repairs if the water intrusion traces directly to the roof impact. Adjusters calculate payouts using local labor rates and material costs current at the time of the loss.
Common Exclusions That Lead to Denied Claims
Policies exclude damage from poor maintenance, such as curled shingles left unrepaired for years or missing flashing around skylights. Wear and tear on roofs older than 15 years frequently results in reduced payouts or outright denial even after a hail event. Cosmetic damage without functional leaks, such as light granule loss on otherwise intact shingles, rarely qualifies for coverage. Flooding from heavy rain that enters through windows or doors falls under separate flood insurance rather than standard homeowners policies. Pre-existing leaks documented in prior inspections can void coverage for related storm claims.
Steps to Document Damage for a Successful Claim
Photograph every impacted area within 48 hours of the storm using close-ups and wide shots that include surrounding landmarks for location reference. Obtain a professional roof inspection report that measures hailstone size and counts hits per square foot. Save weather reports from the National Weather Service showing hail activity in Harris County on the date of loss. Submit the claim promptly and keep records of all communications with the insurer. If the initial offer falls short, request a reinspection before agreeing to repairs.
When Repair Costs Exceed Coverage Limits
When repair estimates reach $8,000 or more for a 1,500-square-foot section, homeowners often compare the insurer's offer against full roof replacement costs listed in the 2026 price guide. Matching older shingles becomes difficult after 8–12 years, prompting some carriers to approve replacement instead of patchwork. In these cases, linking to detailed cost breakdowns helps clarify the decision between targeted roof repair and complete replacement.